How Long Does a Hard Credit Pull Last on Your Report?
A hard inquiry or “hard pull” is when a lender looks at your credit report to decide whether to extend credit. But how long does a hard credit pull last on your credit report? According to Experian, a hard pull can remain visible on your report for up to two years.
A hard pull happens when you officially apply for new credit. A “soft pull,” meanwhile, happens in other scenarios, such as:
Both hard and soft pulls may show up on your credit report.
A hard credit pull can be visible on your credit report for up to two years, but will only affect your credit score for a few months. The impact on your score is usually less than 10 points. Lenders who review your report when deciding whether to extend credit to you may be able to see the hard credit inquiry.
Like hard pulls, soft pulls can also stay on your credit report for up to two years. However, according to Experian, they don’t impact your score.
If you have multiple inquiries close together, lenders may think you’re financially stretched and view you as high risk. While there’s no specific number to stay under, Experian recommends spacing out credit card applications by at least six months.
You now know that it’s not a good idea to get too many hard inquiries too close together. But if you’re shopping for a loan, a credit card, or a mortgage, you probably want to compare rates before you commit.
Getting prequalified can help you understand your potential rates without damaging your credit score, but not all lenders offer this option. So what should you do?
Some people might tell you that there’s a 14-day window when multiple hard inquiries are treated like a single inquiry. Others may tell you that the window is 45 days. Depending on the circumstances, either one could be right.
According to FICO, the company whose credit-scoring model is used by most major lenders, newer scoring models give you a 45-day rate-shopping window, while older scoring models give you 14 days.
To take advantage of the rate-shopping window, it may help to group applications for the same type of credit together. It’s also important to know that rate-shopping windows don’t apply to all forms of credit. They generally apply only to installment credit, such as mortgages, car loans, and student loans, and they almost never apply to credit cards.
If you’ve found yourself asking “How long does a hard credit pull last?” that’s a good thing. It means you’re being mindful of the long-term impacts of applying for more credit. When you understand what happens after a hard pull and why the frequency of hard inquiries is important, you’ll be able to make more informed decisions.
The content provided is intended for informational purposes only. Estimates or statements contained within may be based on prior results or from third parties. The views expressed in these materials are those of the author and may not reflect the view of National Debt Relief. We make no guarantees that the information contained on this site will be accurate or applicable and results may vary depending on individual situations. Contact a financial and/or tax professional regarding your specific financial and tax situation. Please visit our terms of service for full terms governing the use this site.
A hard inquiry or “hard pull” is when a lender looks at your credit report to decide whether to extend...
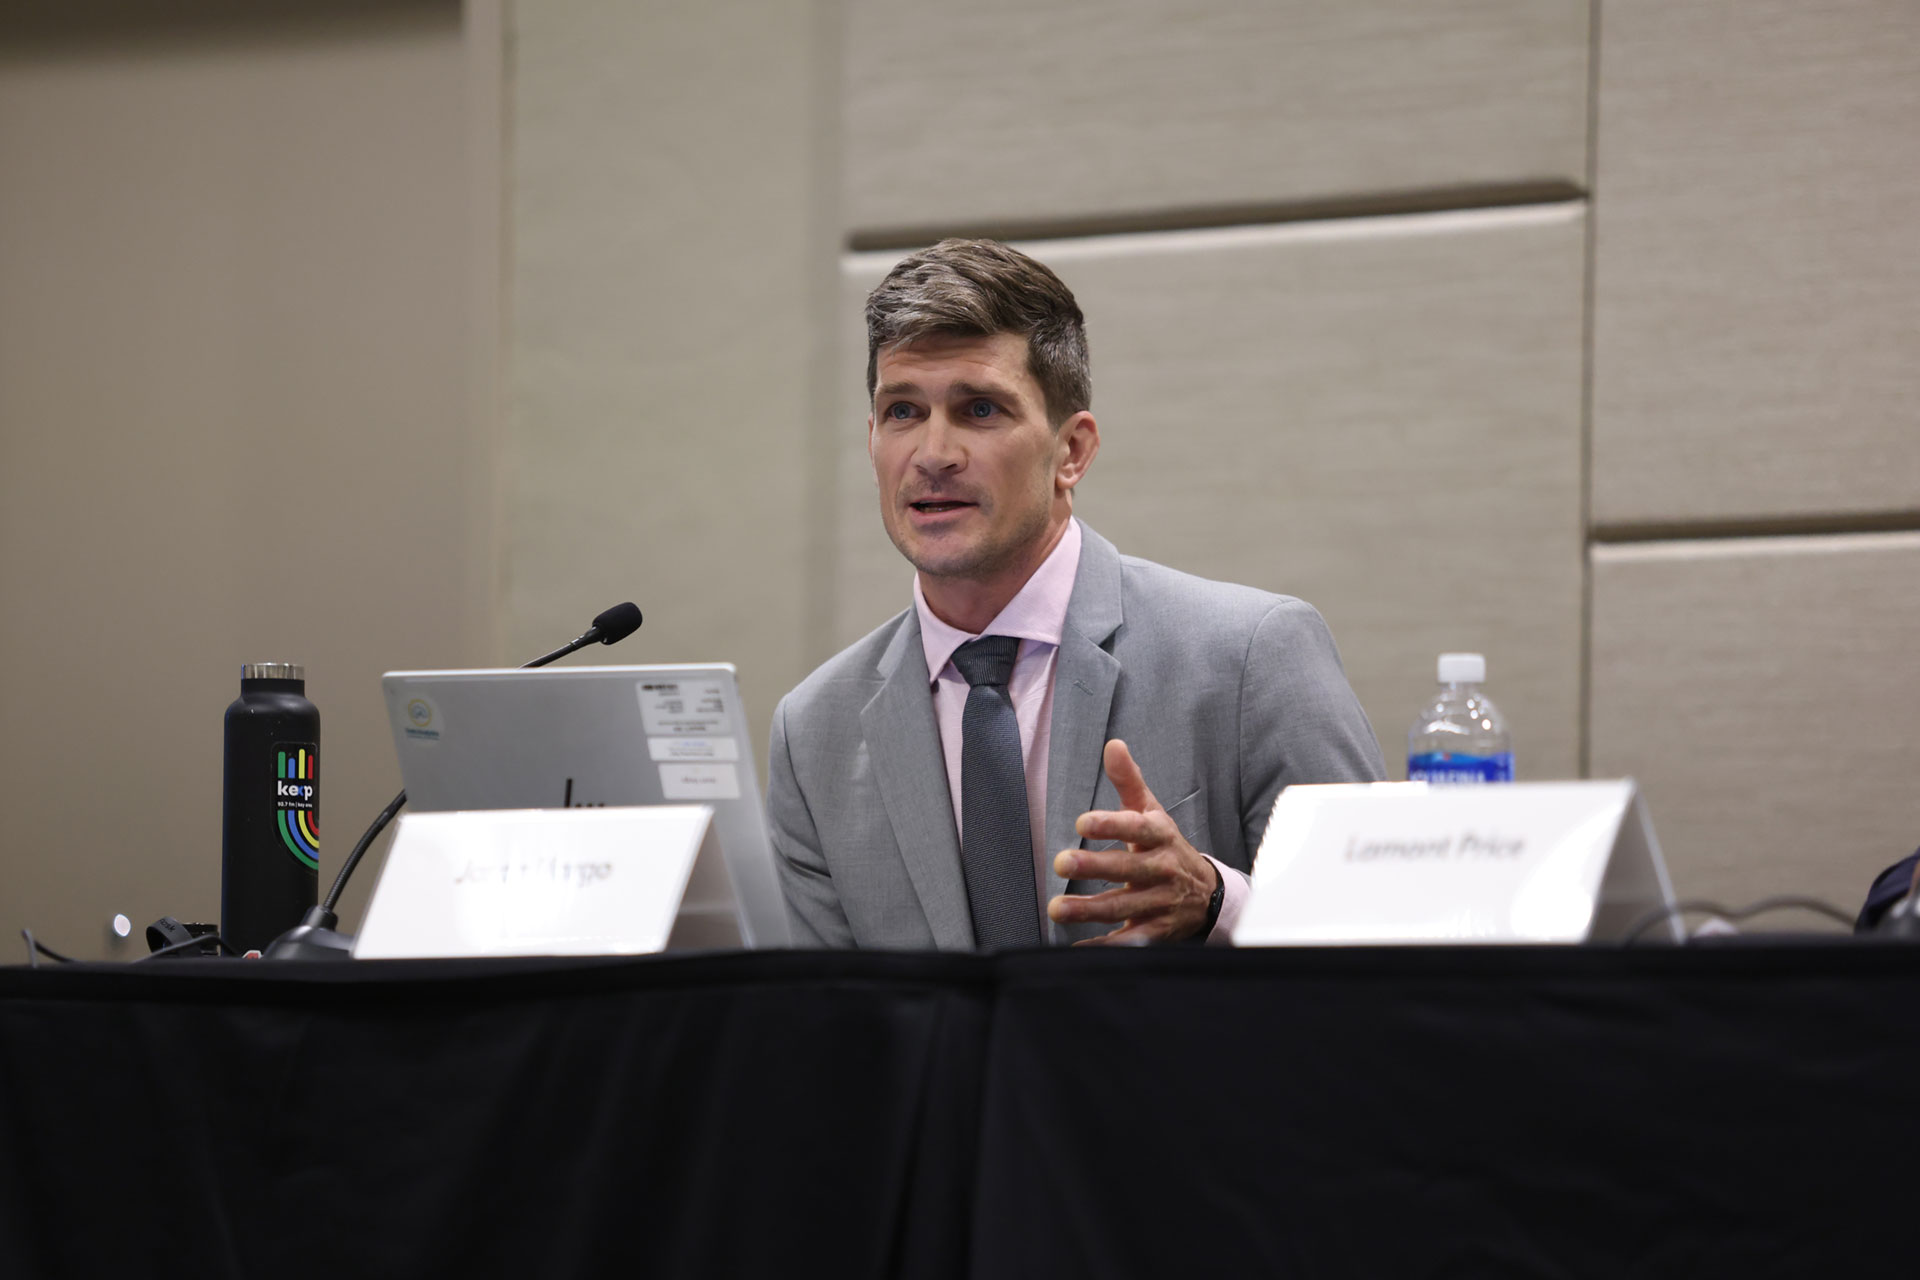
Jason Vargo, senior community development researcher at the Federal Reserve Bank of San Francisco, moderated a session entitled “Leveraging Opportunity...
Podcasts, and Videos Archives UnfavoriteFavorite September 28, 2026 Economic Opportunities Program, and Future of Work Initiative Watch Video Listen to...