Frec Review: Direct Index Investing
Frec is an investing platform offering direct indexing portfolios with low fees. Direct indexing differs from exchange-traded fund (ETF) investing because you own the shares directly. This gives Frec more opportunities to harvest investment losses, which can lower your tax bill.
Direct indexing is generally meant for high-net-worth investors looking to maximize tax-loss harvesting benefits, but Frec makes it available to a larger audience at a relatively low management fee. We explore Frec direct indexing to help you determine if it could make sense for your portfolio.
Frec is a San Francisco-based fintech focused on tax-aware investing. Its main offering is direct indexing, but it provides additional tools for trading, managing cash, and borrowing against investments. The company is a registered financial services provider with the SEC and FINRA and acts as a fiduciary. Behind the scenes, Apex Clearing holds accounts, a major provider of back-end investment accounts. Funds are SIPC insured.
Here’s a closer look at what you can expect with a Frec account.
Direct investing means owning individual stocks to track an index, rather than owning shares of a fund that tracks it, like an ETF. The benefit of direct indexing is that it gives you more control over your holdings, including the ability to sell individual stocks at a loss for tax purposes, even when the overall portfolio has increased in value.
For example, an S&P 500 ETF might be up for the year while some of its holdings are down. With direct indexing, you can harvest those individual losses. In an ETF, you can’t sell the fund’s underlying stocks yourself.
Frec offers three direct indexing options:
Classic: This is Frec’s most straightforward direct-indexing setup. You choose an index, fund your portfolio, and let Frec manage the holdings and check daily for tax-loss harvesting opportunities. You can add, exclude, or reweight up to 25 stocks, with sector adjustments available for most indices.
S&P choices include the S&P 500, S&P 100, S&P 500 Information Technology, S&P 500 Momentum, S&P 500 Shariah, and developed- and emerging-market ADR indices. You can also choose from the Nasdaq-100, Morningstar, Russell, MSCI, Dow Jones, and semiconductor strategies.
Long Short: The Long Short plan adds short positions and additional long positions to an index-based portfolio. For example, a 140/40 split holds long positions equal to 140% of portfolio equity and short positions equal to 40%, targeting net exposure near 100%. You can choose Growth, Value, or Quality tilts.
The goal of Long Short is to create more harvesting opportunities, but be aware that leverage and short selling add risk and financing costs to your portfolio.
Diversify: This plan is designed for investors who hold a large position in one stock. Perhaps you own employer shares with large unrealized gains. Frec builds long and short positions around those shares, and then uses harvested losses to help offset gains as it slowly sells down the large position.
This strategy is obviously more complex than just selling shares or buying an ETF. The benefit is that you may gain tax efficiency, but this isn’t guaranteed.
Frec lets you borrow against eligible investments without selling them, giving you access to cash without triggering a capital gain. The borrowing limit starts around 50% of portfolio value, although it can be as high as 70%. At the time of writing, I noticed advertised interest rates of 4.88%, however the rate is based on the Effective Federal Funds Rate plus 1%, so the rate is variable and subject to change.
You don’t have to make monthly payments as long as you stay within the margin requirements. But if your portfolio falls in value, it may result in a margin call, which could require you to add more assets or repay what you owe. Otherwise, you may need to sell your securities to cover the margin call.
I don’t recommend borrowing money against your investment portfolio. It may seem like an affordable and flexible option, but it is a very high-risk strategy and is not suitable for most investors.
Frec Treasury allows you to invest cash in U.S. Treasury mutual funds. This could be a good option if you want to hold money short-term before investing it or receiving dividends from your portfolio. As of October 15, 2026, Frec is advertising a 3.59% yield. This is a variable rate, and some fund options require at least $1,000.
Frec Treasury Key Features:
Frec Trade lets you buy and sell stocks and ETFs with zero commissions or account minimums. You can select individual tax lots, place market or day limit orders, and transfer eligible holdings from another brokerage without selling them first. Frec uses Plaid, a third-party secure transfer service, to accommodate share transfers.
While Frec Trade shouldn’t be mistaken for a dedicated online brokerage like Charles Schwab or Fidelity, it covers the basics and lets Frec clients manage individual investments alongside their Frec direct indexing portfolios. That said, watch for overlapping trades. Buying a stock yourself around the time Frec sells it at a loss could create a wash sale and affect any tax benefit.
Tax-loss harvesting is one of Frec’s competitive advantages. It checks direct indexing portfolios daily for opportunities to sell stocks below their purchase cost and reinvest while keeping the portfolio aligned with its strategy.
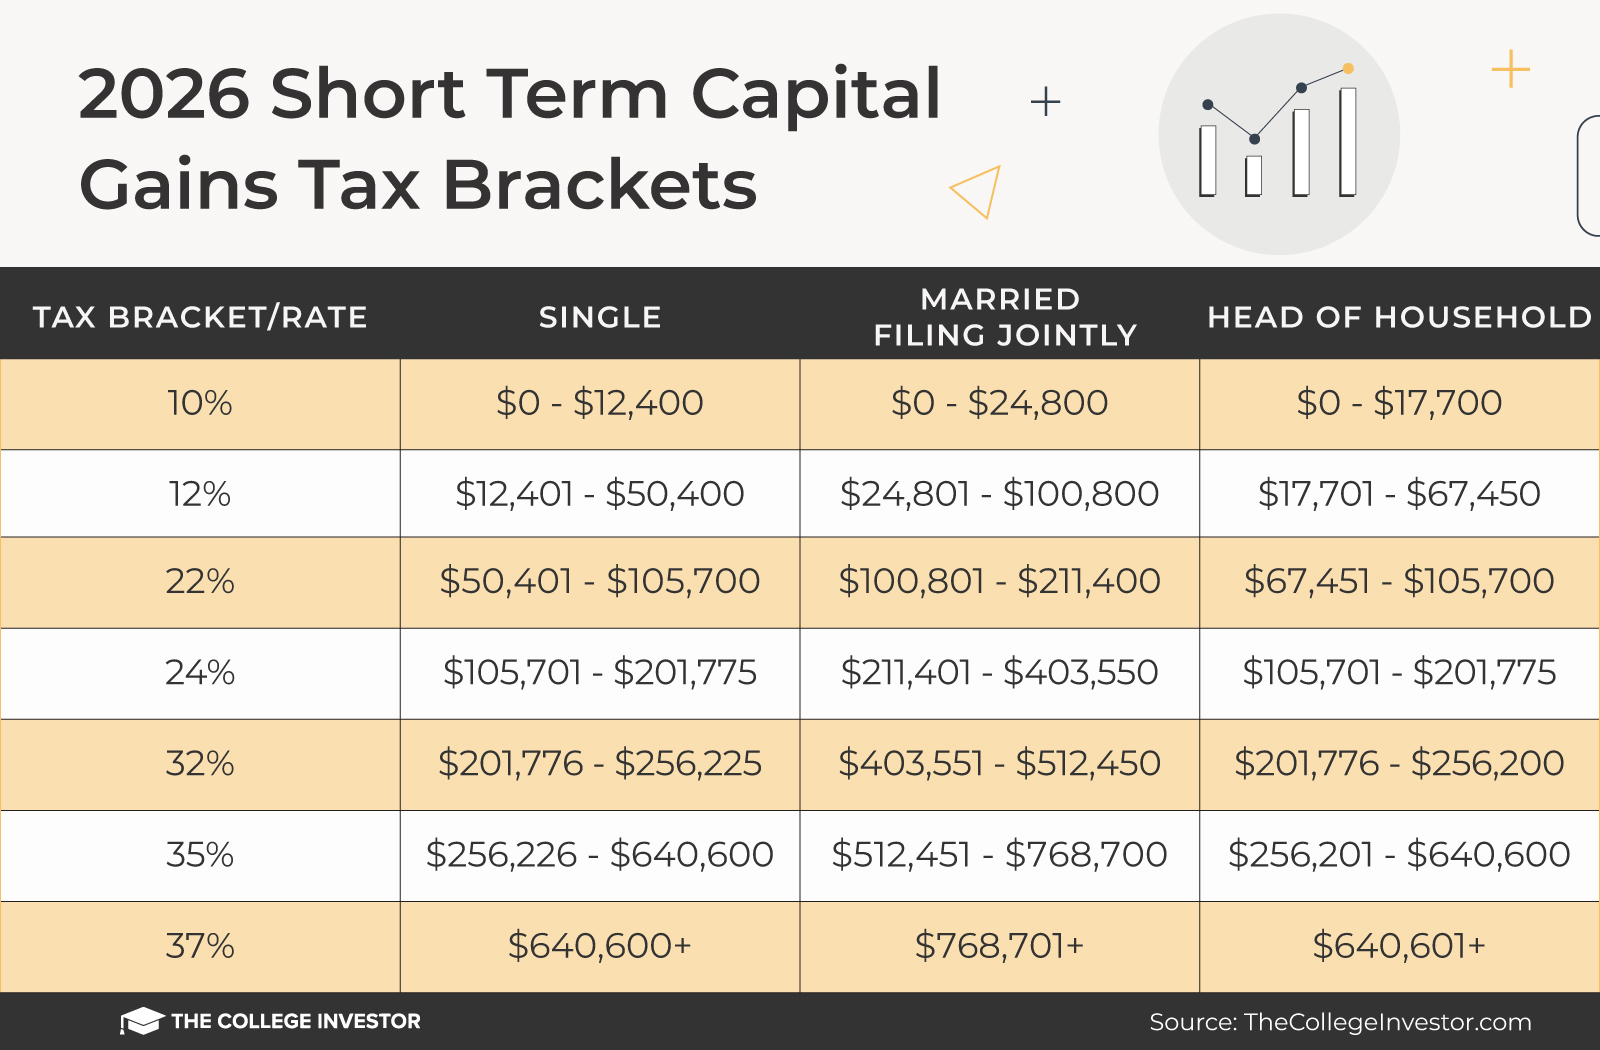
You can use those realized losses to offset capital gains. According to the IRS, excess net losses can generally offset up to $3,000 of ordinary income annually ($1,500 if married filing separately), with unused losses carried forward.
Frec does its best to avoid wash sales, but it can’t account for trades you place in outside accounts (including your spouse’s accounts), and any conflicting self-directed trades that you make. How much you benefit from this feature will depend on your tax situation, available gains, market conditions, and costs.
The table below breaks down the annual fees you can expect to pay for the various Frec accounts:
Note that you may incur other costs when dealing with Frec. This includes post-tax financing costs in the Long short and Diversify accounts.
Frec’s competitors include robo-advisors, online brokerages, and other direct indexing investment platforms. Some top competitors include:
Large investment companies like Fidelity and Charles Schwab offer direct indexing products. Large brokerage firms offer one-size-fits-all versions of direct indexing, with fully managed portfolios as the primary option.
In many cases, robo-advising platforms are already optimized for tax loss harvesting, so adding a direct indexing product makes sense. Wealthfront is an example of a robo-advisor that offers direct indexing. It requires a portfolio of at least $100,000 for direct indexing, five times the minimum with Frec. Wealthfront charges 2.5 times more than Frec, with a 0.25% annual fee. Betterment is similar to Wealthfront, but while they offer tax loss harvesting, they do not offer direct indexing.
It’s easy to get started with Frec. Go to the Frec website and click the button at the top to start opening an account.
You can create an account with your email and a password or by linking to a Google or Apple account. After entering your login details, you can choose three account types: Individual, trust, or business. You’ll need to add your personal information, such as your address and a verified phone number, to continue setup.
Then you’ll link your bank account or set up another funding method to meet the $20,000 minimum and choose your initial index portfolio.
If you’re computer savvy, it takes about two minutes to set up an account.
Frec portfolios come with the same risks as other indexed invested portfolios. As a company, Frec is safe to deal with. Apex Clearing holds Frec accounts, and Frec is a licensed and registered investment company with both the SEC and FINRA.
Investment accounts are SIPC insured, so you’ll get your assets back even if Frec or Apex Clearing go out of business. I’ve invested with a company that shut down and used Apex Clearing, and it was easy enough to get my money out and tax statements even after the investment company closed.
You can email Frec at [email protected]. The website also has a link to schedule a call with the team, as well as a fairly robust self-help section with answers to common questions.
I think Frec is a compelling option for investors with taxable assets, significant capital gains they can offset, and the flexibility to customize their stock exposure. Its broad index selection gives it a competitive edge over other platforms with only a few choices.
That said, just because you qualify for a Frec account doesn’t mean it’s the right fit. A low-cost ETF may be more than enough if you mainly want market exposure and don’t have much use for harvested losses. If you’re interested in Frec, I recommend starting by comparing its Classic tier with a suitable ETF or other competing direct indexing accounts. Only consider Long Short or Diversify if you need the strategy those accounts offer and understand the added costs and risks.
Classic direct indexing starts at $20,000. Annual fees start at 0.09%. Index choices include S&P, Nasdaq, Morningstar, Russell, and MSCI...
After spending years working in Salesforce Marketing Cloud, you start to realize that building a journey is rarely the difficult...
Author Rod Khleif: Top Multifamily Real Estate Mentor, Best Selling Author & Host of Top Real Estate Investing Podcast I...